Investment Banking Advisory vs Business Broker for Sub-$10M Deals
Listing models and managed auctions reach fundamentally different buyers.
An owner returns a call, listens to a confident pitch about getting the business sold, and hangs up having never asked the one question that actually determines the outcome: how, mechanically, will this person create competition for the business? That gap matters because "business broker" and "M&A advisor" are largely unregulated titles in most U.S. states. A number of states require business brokers to hold a real estate license, and anyone can print "investment banker" on a card, though actually performing investment banking activities through a broker-dealer requires a FINRA Series 79 license. None of that licensing structure tells a seller what will happen to their deal once they sign. A broker runs a listing model, but an M&A advisor runs a managed competitive auction, and that difference is what lets you choose based on mechanics, not job titles. This matters most for founder-led businesses across a wide range of deal sizes, where the process model chosen can decide whether the right buyer pool is ever reached.
How the listing model works and what it is optimized for
But you should understand the broker's listing model on its own terms before you decide it is the wrong fit. A business broker takes an anonymized profile of the business and posts it to public marketplaces, then fields inbound interest as buyers find it and helps negotiate the deal that results. That is a listing model, built to do one job well: connect an owner-operator business with an individual who wants to buy a job or a small operating company, not with an institutional acquirer running a dedicated deal team. The valuation math reflects that audience. Brokers price on seller's discretionary earnings (SDE) multiples and rules of thumb rather than recast EBITDA or discounted cash flow, and for the kind of business this model serves, SDE is the right lens, not a compromise. Retail locations, franchises, restaurants, single-location service businesses: these are owner-operator companies where the buyer will run daily operations personally, and a broker's network of individual buyers and financing contacts is precisely the pool that produces a sale. One industry association puts the Main Street segment at under $2 million in transaction value, and the Lower Middle Market at $2 million to $50 million. Brokers who consistently close deals above the $2 million line are already operating in territory that overlaps with what M&A advisors do, which says something about how porous the boundary actually is in practice. The one structural cost built into the listing model is confidentiality. A public profile, even anonymized, can be pieced together by employees, customers, and competitors who know the industry well enough to recognize the numbers. If the business has a simple cash flow, no key-person risk, and no sensitive customer concentration, you barely notice that exposure. For a business where a competitor learning of the sale could trigger customer defections or where an employee's departure could tank earnings mid-process, the same exposure becomes a real liability.
What the managed competitive process does differently, step by step
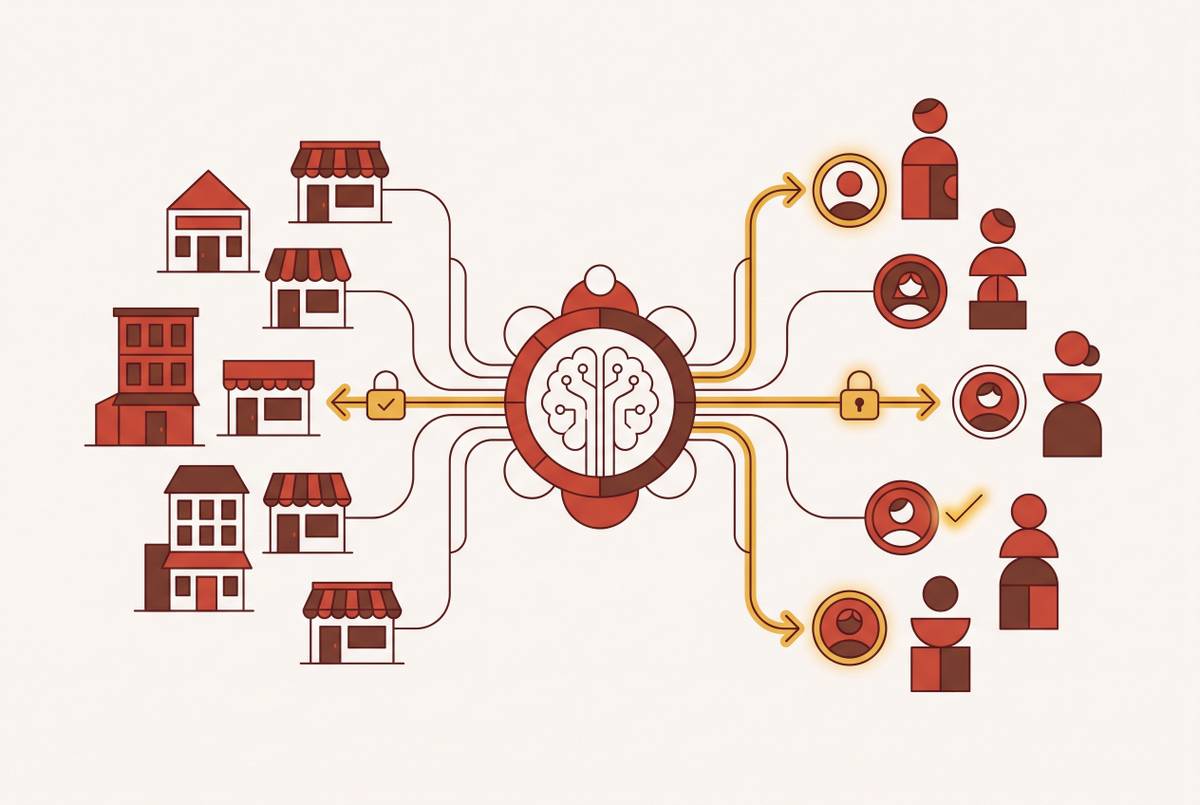
An M&A advisor's process exists to manufacture competitive tension, because that tension is what reliably pushes a closing price above whatever a buyer first offers. The sequence starts before a single buyer is contacted. The advisor does not post a public listing; instead, they prepare a blind teaser that withholds the company's name and identifying details, and only release a full confidential information memorandum once a prospective buyer has signed a non-disclosure agreement. Confidentiality is engineered into the structure of the process itself. Outreach follows, and it looks nothing like waiting for inbound calls: the advisor contacts specific partners at specific private equity firms and strategic acquirers by name, built on relationships maintained over time with those buyers and platforms. This named, relationship-driven access is a fundamentally different model than a marketplace listing, reaching people who were never going to browse a public site. Once interest is confirmed, the process runs in staged rounds, indications of interest first, then letters of intent, keeping several buyers engaged in parallel. A single buyer negotiating alone has every incentive to bid at the floor of what they think the business is worth. When multiple qualified buyers bid against each other, aware that other parties are at the table, that is what actually moves the number upward. Valuation throughout is built on recast EBITDA, discounted cash flow, and precedent transaction multiples, the language institutional buyers and their lenders actually use when underwriting a deal, rather than the SDE shorthand that works for an individual buyer. And the negotiation itself extends well past headline price, into earnouts, working-capital pegs, escrow holdbacks, rollover equity, and indemnification provisions, all negotiated against professional counterparties who structure these terms for a living. The managed process's reliance on targeted outreach to named buyers and staged bid rounds to manufacture competition is exactly the buyer-matching problem that AI-driven platforms have started to address, identifying which institutional acquirers and PE platforms are genuinely active in a specific business type and reaching them with precision instead of guesswork, so the competition that drives price is real rather than assumed.
If the business is small enough, the broker model is usually the choice that makes economic sense. The buyer is almost certainly an individual, so SDE is the right valuation lens for that buyer's financing and operating plans, and advisor fees would eat a disproportionate share of proceeds relative to what a competitive process could realistically add. Once you climb past a certain enterprise value, private equity firms and strategic acquirers are not browsing public marketplace listings, so if you run the listing model there, you stay structurally invisible to the buyer pool most able to pay a premium. Size alone will not settle it. One might argue the deal's dollar value should be the deciding factor, but the sharper test is who is actually going to buy this business. If the most likely acquirer is an individual operator or a financed buyer, the broker model reaches that pool efficiently and at lower cost. If the most likely buyer willing to pay a premium is a PE-backed platform or a strategic acquirer running an add-on strategy, only an advisor's curated, named outreach is going to find them. A seller at a given mid-sized enterprise value in one of those sectors is looking at a fundamentally different buyer landscape than a seller at the same dollar figure running a single retail location, as the next section explains.
Private equity's move downmarket has quietly rewritten the old rule of thumb that said broker territory ends well below the middle band and advisor territory starts well above it. PE firms pursuing buy-and-build strategies acquire a platform company in a target sector, then add smaller businesses to it as bolt-on acquisitions, so businesses with modest EBITDA that would have been entirely invisible to institutional capital five or ten years ago now get inbound interest from PE-backed acquirers actively hunting for them. But how does this affect a seller who has already decided to list with a broker? A listing on a public marketplace will not reach a PE-backed platform company's corporate development team. That team works from sector maps, broker and advisor relationships, and direct outreach lists, and the only way a seller's business appears on that radar is through the kind of targeted, named outreach an advisor's process runs. The practical consequence is straightforward: the right buyer pool for a sector-attractive smaller business now includes institutional acquirers capable of paying strategic premiums, but only if the seller's process is actually built to reach them. If you run the listing model in a sector with active PE buy-and-build activity, you are not simply reaching fewer buyers overall. They are missing the specific category of buyer most likely to pay above what an individual operator would ever offer, which turns the size threshold from the earlier section into less of a hard line and more of a sector-dependent judgment call.
The retainer risk and three other objections worth taking seriously
The strongest argument against hiring an advisor for a smaller deal holds up under scrutiny, but it applies to a specific subset of businesses rather than to the category as a whole, and it deserves a straight answer. Retainer risk is the sharpest version of the objection: if a business is likely to sell at a price where the advisor's minimum success fee works out to a high effective rate, higher than a broker's straight 10% commission, that is a genuine economic problem when the business lacks the characteristics that justify running a competitive process. This risk is real for businesses that are borderline salable, heavily dependent on the owner's personal relationships, or sitting in a sector with no institutional buyer interest, and those businesses belong with a broker regardless of enterprise value. A second objection concerns process quality itself: not every firm calling itself an M&A advisor actually delivers advisor-quality execution, and paying advisor-level fees for a process that functions like business brokerage produces the worst possible economics, fees without the competitive tension that is supposed to justify them. The label on the engagement letter guarantees nothing here, so the next section asks what does. A third objection concerns speed: brokered deals that close tend to close faster than advisor-run processes. But a large share of brokered listings never sell at all, because the listing model does not screen for salability the way an advisor's intake process typically does before accepting a mandate, so the speed advantage only applies to the subset of listings that were always going to sell easily. A fourth objection concerns attention: when a large bank accepts a mandate below its usual minimum deal size, the engagement often gets junior staffing, and the senior partners who won the pitch meeting are not the ones running the day-to-day process. A boutique advisor for whom a smaller deal is a genuine priority, not a rounding error against a much larger book of business, avoids this failure mode, but a seller still has to confirm that directly rather than assume it.
What to Ask Any Intermediary Before Signing a Mandate
Because neither "business broker" nor "M&A advisor" is a regulated title, the only real protection a seller has is asking questions precise enough to reveal which process model the person across the table is actually going to run, regardless of what their card says. Asking for the last five closed deals by enterprise value and sector is the single most revealing question you can ask, because the answer immediately shows whether a firm operates in the seller's weight class or is pitching a size range it rarely actually closes. Asking how the firm plans to create competition separates the two models faster than any credential: a listing-model answer describes posting the business on marketplaces and fielding inbound calls as they arrive, while a managed-process answer describes building a named buyer list, running staged indication-of-interest and letter-of-intent rounds, and managing several buyer conversations in parallel. Who will staff the engagement day to day matters just as much: a boutique lower-middle-market advisor where senior partners personally run the deal avoids the attention problem that can afflict a larger bank handling a mandate well below its usual minimum. Asking how confidentiality will be protected surfaces a materially different risk profile depending on the model: a broker's answer typically involves a blind profile and NDA collection from whoever responds to the listing, while an advisor's answer involves a blind teaser, an NDA-gated release of the full confidential information memorandum, and outreach limited to a curated list of named buyers, a distinction that matters enormously for a business with real exposure to employees, customers, or competitors learning of the sale prematurely.